Reduce the Financial Impact of a Large Wind & Hail Deductible
A wind or hail claim can leave a homeowner facing a significant out-of-pocket expense before the underlying home insurance policy pays. Deductible buyback coverage may provide a companion layer of protection designed to help manage that financial exposure.
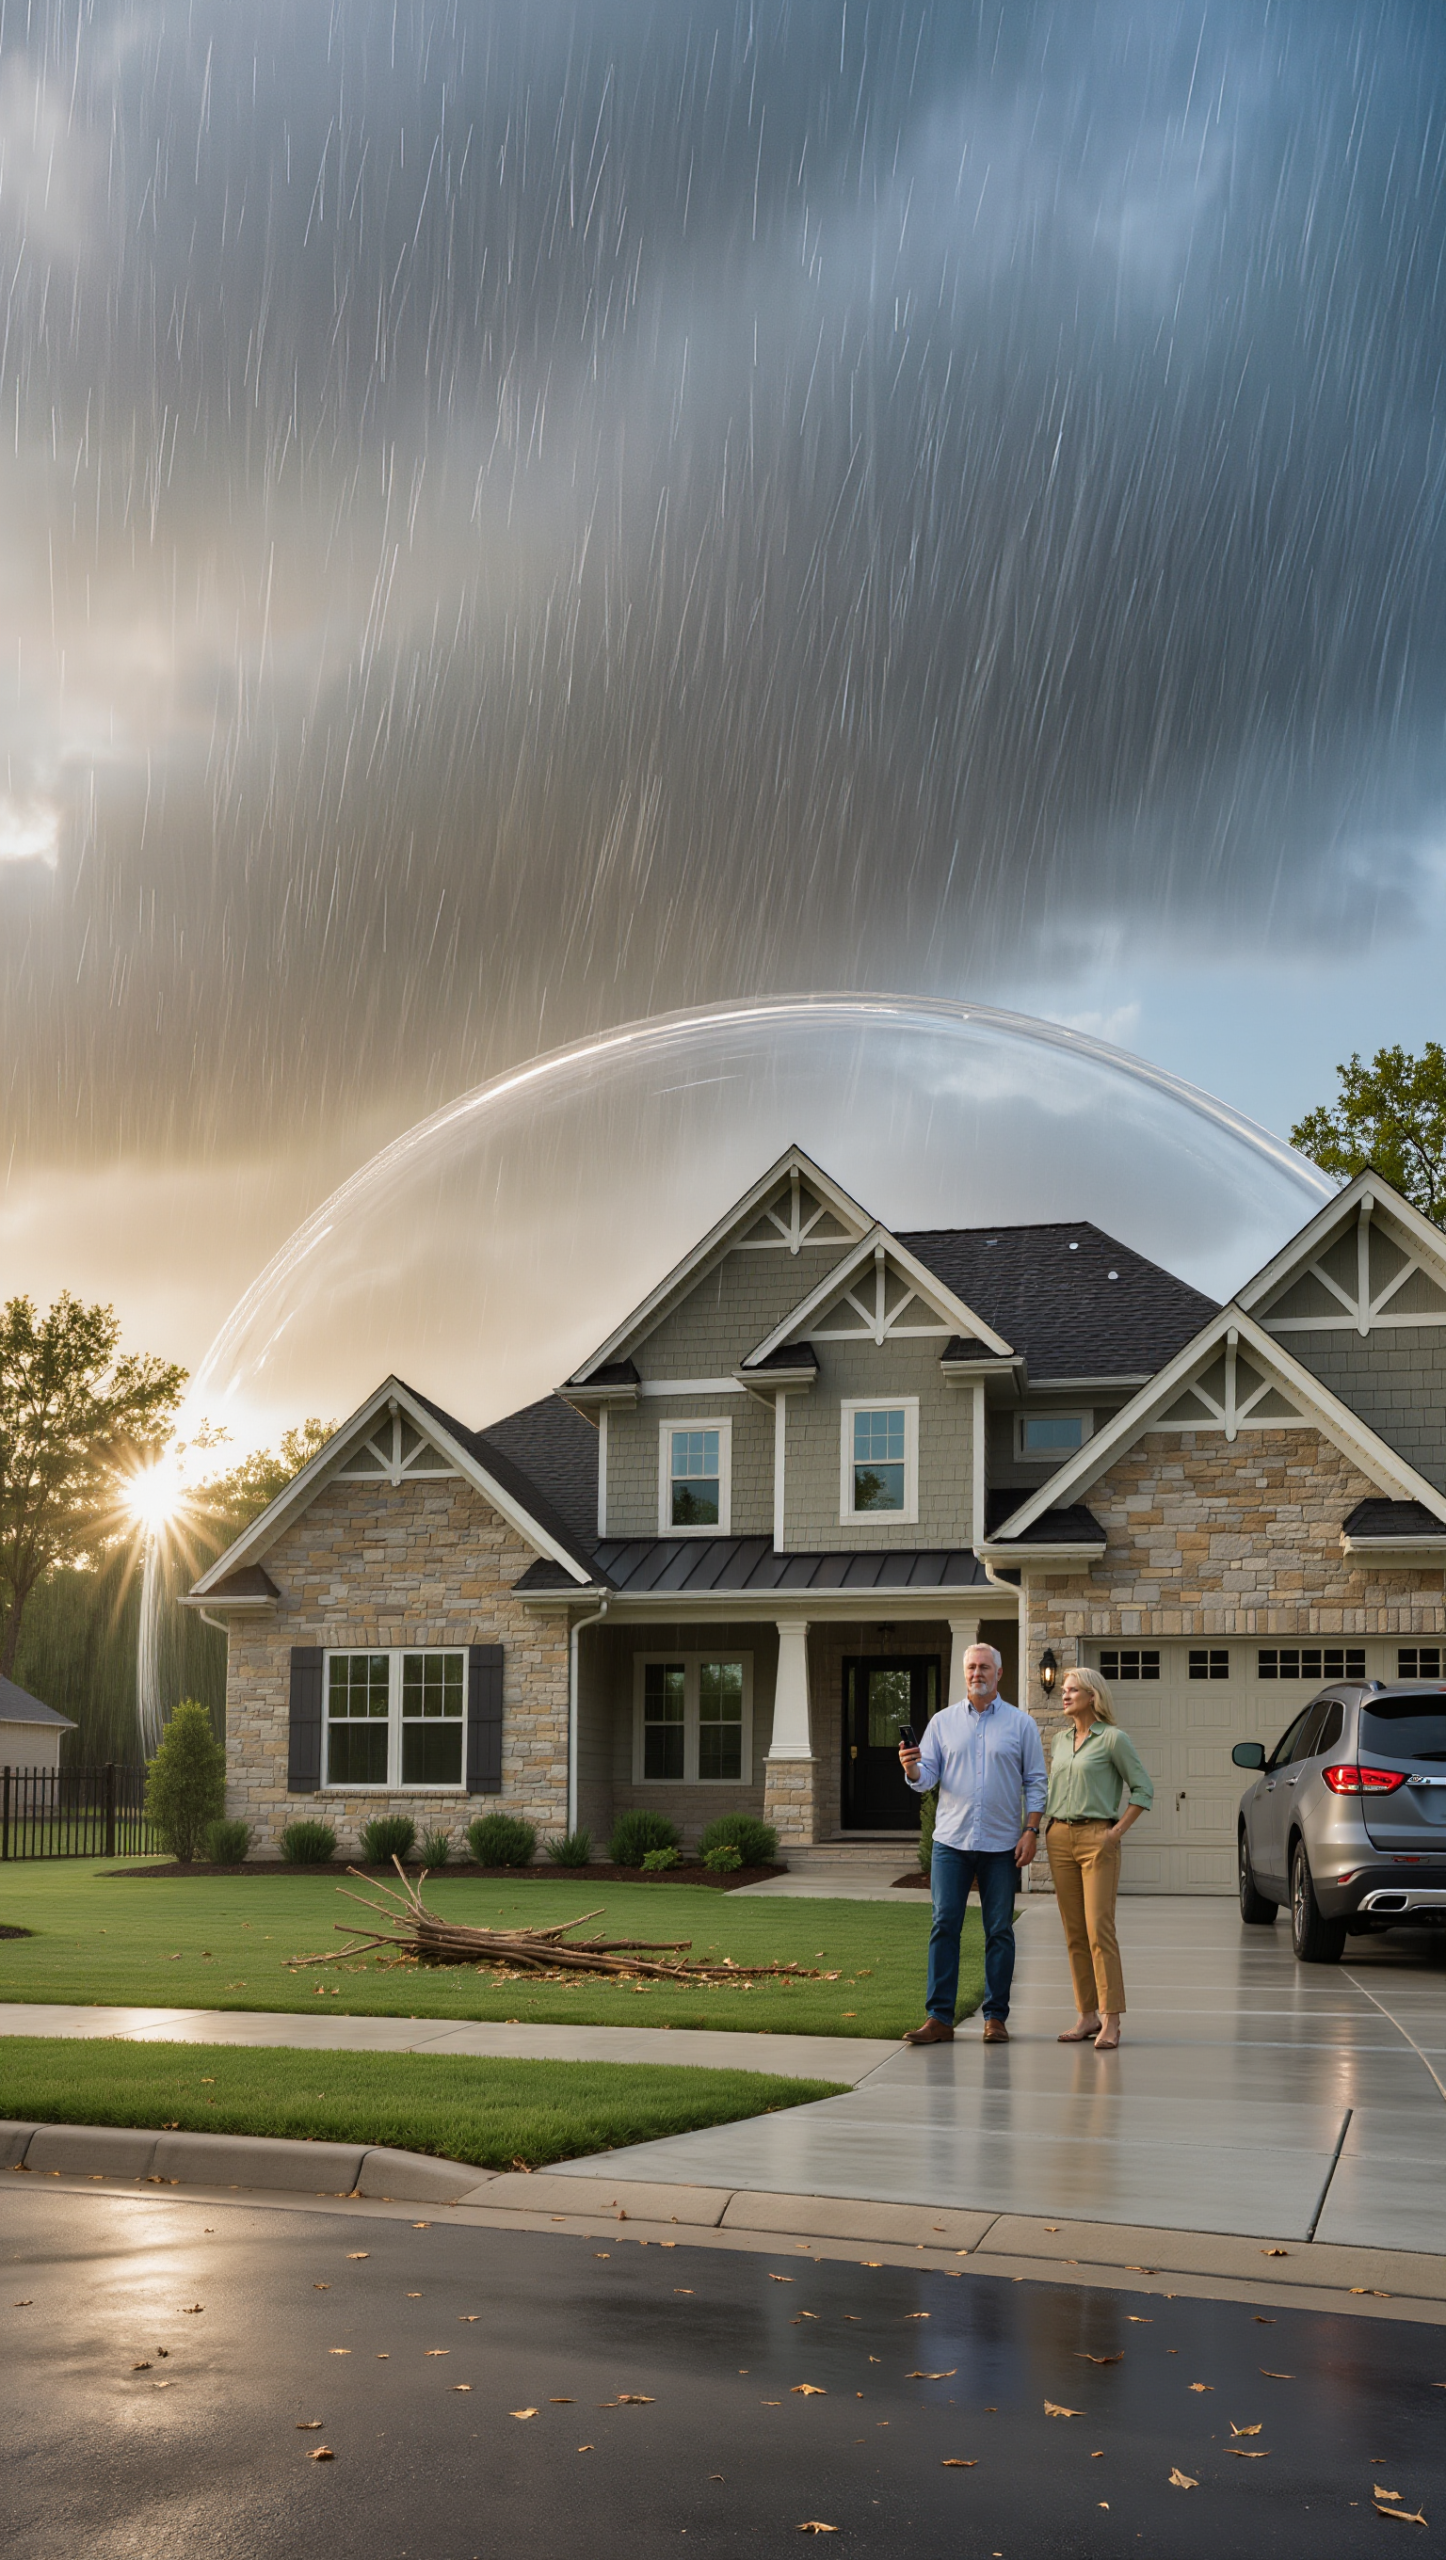
Your Wind & Hail Deductible Can Be a Major Out-of-Pocket Expense
Home insurance deductibles are the portion of a covered claim you are responsible for paying before the insurance company pays the remaining covered loss. In Texas, wind and hail losses may have a deductible that is different from the deductible that applies to other types of damage.
Some policies use a percentage deductible instead of a fixed dollar amount. That means the actual amount you could pay after a covered storm can depend on the insured value of your home.
A deductible buyback policy, sometimes called a deductible buy down, may provide an additional layer of protection designed to help offset some or all of a qualifying underlying deductible.
If your home has a percentage wind and hail deductible, ask your insurance agent to show you exactly what that percentage means in dollars. Understanding the potential out-of-pocket cost can help you decide whether additional deductible protection makes sense for you.
A Companion Policy for Your Existing Home Insurance
Deductible buyback coverage is designed to work alongside an underlying property insurance policy. When a qualifying wind or hail loss occurs and the underlying policy responds, the companion policy may provide benefits according to its own terms and limits.
The goal is simple: help reduce the financial burden created by a large storm deductible without necessarily replacing your existing homeowners insurance policy.
Keep Your Existing Home Policy
A deductible buyback policy may be structured as additional coverage that works alongside your existing homeowners or dwelling policy.
Designed Around Wind & Hail
These products can focus specifically on the financial exposure associated with qualifying wind and hail losses.
Help Manage Out-of-Pocket Costs
Depending on the policy selected, available benefits may help offset some or all of an eligible underlying deductible.
Two Layers of Protection
Deductible buyback coverage is not a replacement for homeowners insurance. It is designed to complement an underlying policy when the requirements of both policies are satisfied.
| Underlying Home Policy | Deductible Buyback Policy |
|---|---|
| Provides the primary property coverage for covered losses according to the terms, limits, exclusions and deductible shown on the policy. | Provides additional benefits according to its own policy terms when a qualifying event occurs. |
| May include a wind and hail deductible that is separate from other property deductibles. | May be designed to help offset the financial impact of a qualifying underlying wind and hail deductible. |
| Remains the primary property insurance policy for covered losses. | Acts as a companion layer rather than replacing the underlying homeowners or dwelling policy. |
Why Homeowners Should Pay Attention to Their Storm Deductible
Texas homeowners can experience severe thunderstorms, hail and damaging winds. The Texas Department of Insurance recommends that homeowners understand their deductibles, including whether the wind and hail deductible differs from the deductible for other types of damage.
Percentage deductibles deserve particular attention because the dollar amount can be much larger than a homeowner expects. For example, a percentage deductible is calculated against the applicable insured amount rather than simply being a predetermined dollar figure.
Before buying or renewing a home insurance policy, it is worth asking what your wind and hail deductible is, how much it represents in dollars and whether there are additional options available to help manage that exposure.
Percentage Deductibles
A percentage deductible can translate into a substantial dollar amount depending on the home’s insured value.
Roof Damage
Wind and hail are common concerns for Texas homeowners, making it important to understand how your policy treats roof damage and storm deductibles.
Financial Preparedness
Knowing the potential out-of-pocket cost before a storm can help you evaluate whether additional deductible protection is appropriate.
Deductible Buyback vs. Standalone Wind & Hail Coverage
Deductible buyback is not the only way to approach wind and hail exposure. Depending on your property, location, existing insurance and eligibility, a standalone wind and hail policy may also be an option.
The two approaches are not identical. A deductible buyback generally works as a companion to an underlying policy, while standalone wind and hail coverage is designed to provide its own storm-related protection according to the policy terms.
| Option | How It Works | May Be Considered When… |
|---|---|---|
| Deductible Buyback | Companion coverage designed to provide benefits associated with a qualifying loss under an underlying property policy. | You want to keep your existing home policy while addressing the financial impact of a large qualifying deductible. |
| Standalone Wind & Hail | Separate coverage designed specifically around wind and hail risks, subject to its own terms, limits and eligibility requirements. | You want to explore separate storm coverage or an alternative structure for managing wind and hail exposure. |
Availability, eligibility, covered causes of loss, limits, deductibles and claim requirements vary by insurance company and policy. Not every option is available for every property.
Review Your Home Insurance First
Deductible protection starts with understanding the policy you already have. Your homeowners policy determines the underlying coverage, applicable deductibles, limits and exclusions that may affect a storm claim.
If you are shopping for a new policy, our Texas Home Insurance page can help you understand the broader coverage before considering additional deductible protection.
Deductible Buyback May Be Worth Discussing If…
There is no single deductible strategy that is right for every homeowner. A deductible buyback option may be worth discussing if your existing policy leaves you with a storm deductible that would be difficult to pay comfortably.
You Have a Large Wind & Hail Deductible
Your policy may use a percentage deductible that represents a significant dollar amount after a covered storm.
You Prefer More Predictable Financial Exposure
Additional deductible protection may help you plan for the financial impact of a qualifying storm loss.
You Want to Compare Alternatives
An independent agent can help you compare available home insurance and supplemental options rather than looking at one policy in isolation.
Understand Your Roof Coverage Before the Next Storm
Wind and hail losses frequently raise questions about roof coverage, deductibles, replacement cost and actual cash value. Your policy may also treat roof damage differently depending on the age, condition and construction of the roof.
The Texas Department of Insurance recommends asking your agent whether your wind and hail deductible is different from your other property deductible and how your policy would respond to roof damage.
Let’s Look at Your Options
We make it easier to understand your current deductible and explore available solutions.
Tell Us What You Have
Share your current home insurance information and wind and hail deductible.
We Compare Options
We review available deductible buyback and wind and hail solutions based on your property and needs.
You Choose Your Coverage
Choose the option that fits your coverage goals and financial comfort level.
Related Coverage From Lavon Insurance
Deductible protection is only one part of a complete insurance strategy. Explore related coverage options available through Lavon Insurance.
Deductible Buyback for Texas Homeowners
Lavon Insurance is an independent insurance agency serving customers throughout Texas, with a strong local focus on Lavon and surrounding North Texas communities. We can help you review your existing coverage and explore available options from multiple insurance companies.
Deductible Buyback FAQ
What is deductible buyback insurance?
Deductible buyback insurance is a companion insurance product designed to help offset the financial impact of a qualifying deductible under an underlying property insurance policy. Coverage varies by policy.
Is deductible buyback the same as deductible buy down?
The terms are sometimes used to describe similar types of supplemental deductible protection. However, the actual coverage, limits and claim requirements depend on the specific policy.
Does deductible buyback replace my homeowners insurance?
Generally, a deductible buyback policy is designed as companion coverage rather than a replacement for homeowners insurance. The underlying policy remains important and its terms still apply.
What is a wind and hail deductible?
A wind and hail deductible is the amount you are responsible for paying on a covered wind or hail claim before the underlying insurance policy pays according to its terms. It may be different from other deductibles on the policy.
Can my wind and hail deductible be a percentage?
Yes. Some property policies use percentage-based deductibles. The Texas Department of Insurance recommends understanding how a percentage deductible translates into an actual dollar amount for your home.
Can deductible buyback cover my entire deductible?
Some products may be designed to provide benefits that cover part or all of a qualifying deductible, while others may have specific limits. The available amount depends on the product and underwriting requirements.
Does every Texas homeowner qualify for deductible buyback?
No. Availability and eligibility can depend on the property, existing insurance, location, coverage terms and underwriting requirements.
Is standalone wind and hail insurance the same thing?
No. Standalone wind and hail coverage is a separate approach designed to provide storm-related protection under its own policy. Deductible buyback is generally structured as companion coverage for an underlying property policy.
Can I get deductible buyback if I already have homeowners insurance?
In some cases, yes. Deductible buyback is specifically designed as companion coverage, but eligibility depends on the specific product and your existing policy.
How do I find out what my wind and hail deductible is?
Review your homeowners insurance declarations page or contact your insurance agent. Ask specifically whether your policy has a separate wind and hail deductible and what that deductible equals in dollars.
Don’t Wait Until After the Storm
Let Lavon Insurance review your current wind and hail deductible and help you explore available deductible buyback and storm protection options.
Insurance coverage, eligibility, deductibles, limits, exclusions, premiums and claim requirements vary by insurance company and policy. Deductible buyback and standalone wind and hail products may not be available for every property or customer. This page is for general informational purposes and does not amend, replace or supersede any insurance policy. Please review your policy documents and speak with a licensed insurance professional about your specific situation.