Mobile Home Insurance in Texas
Your manufactured home is your home. Protect it with insurance designed for the way manufactured and mobile homes are built, owned and used.
Lavon Insurance is an independent Texas insurance agency that can compare available mobile and manufactured home insurance options from multiple carriers.
Insurance Designed Around Your Home
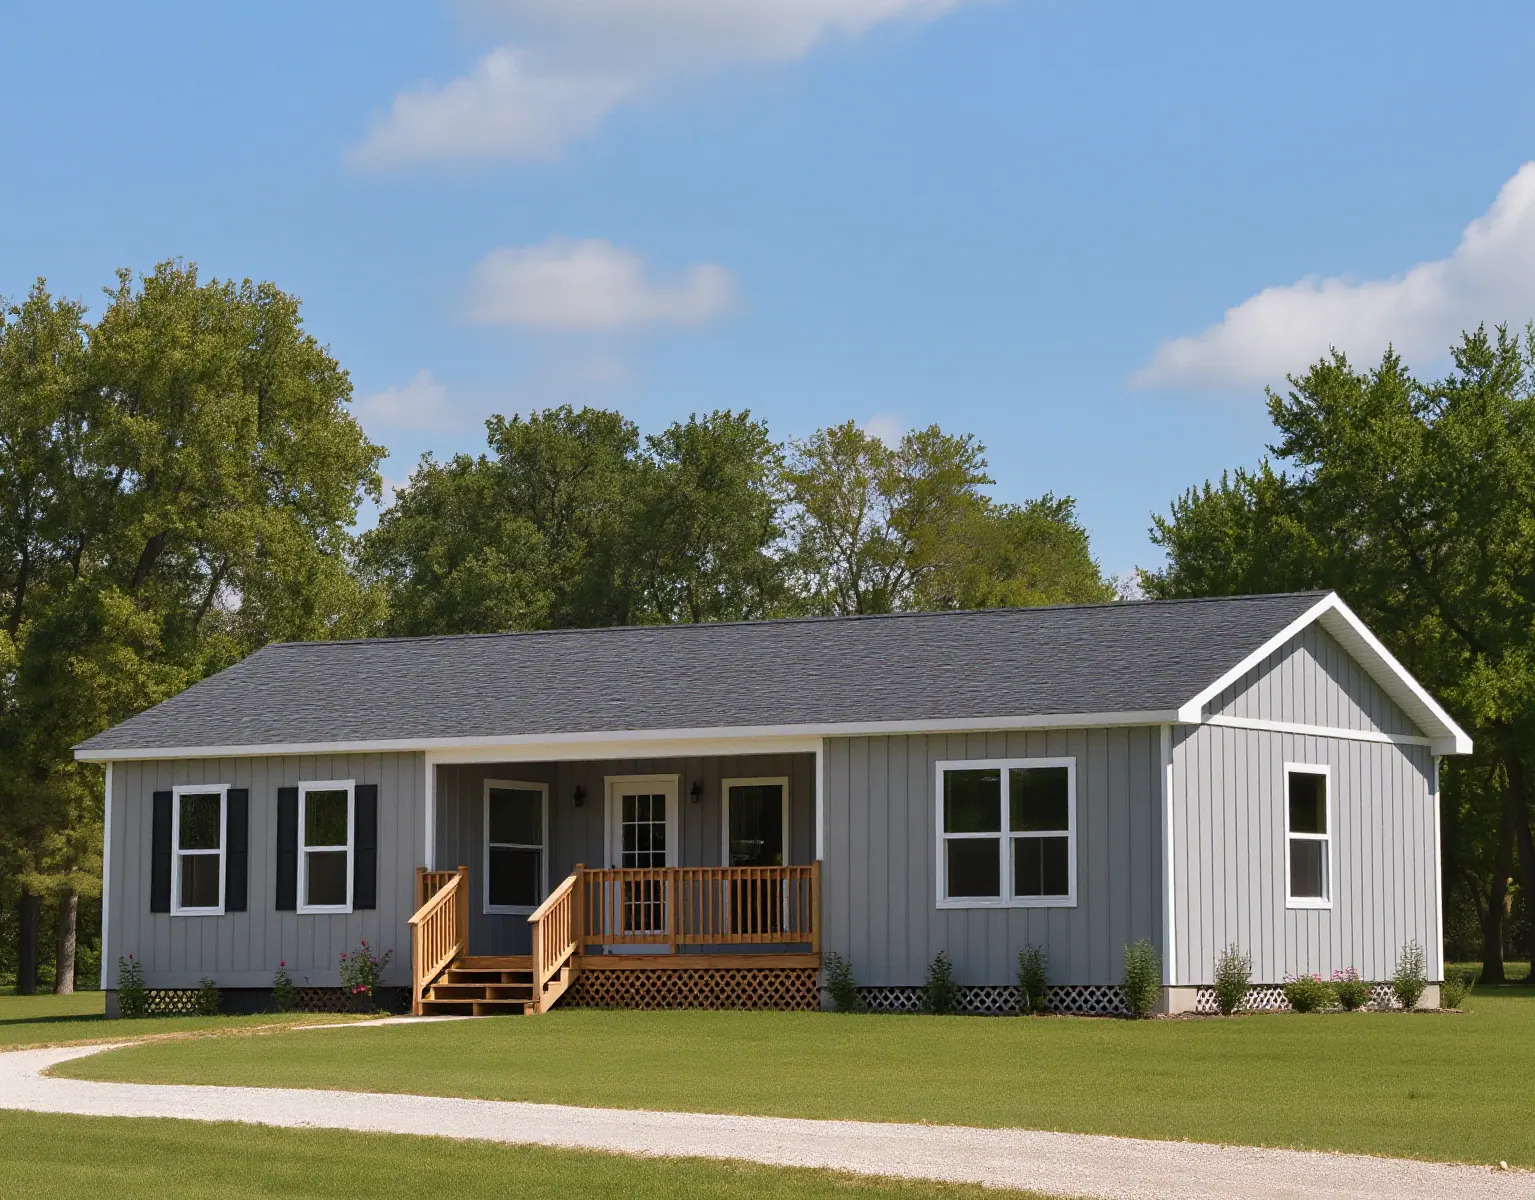
Mobile and manufactured homes can have different insurance needs and underwriting requirements than traditional site-built houses.
A mobile home insurance policy may help protect the home itself, your belongings, personal liability and additional living expenses after a covered loss.
Because insurance companies can differ significantly in the types and ages of manufactured homes they accept, working with an independent agency can make comparing options easier.
Tell Us About Your Home
- Year manufactured
- Manufacturer and model
- Single-wide, double-wide or multi-section
- Current location
- Home condition and updates
- Whether you own or lease the land
- Decks, porches, sheds and additions
- Approximate value of your belongings
What Can Mobile Home Insurance Cover?
Coverage varies by insurance company and policy form, but mobile and manufactured home policies commonly include several important types of protection.
Dwelling Coverage
Helps protect the manufactured or mobile home itself against covered causes of loss, subject to the policy terms, limits and deductible.
Personal Property
May help protect furniture, clothing, electronics, appliances and other covered belongings inside the home.
Personal Liability
Can help protect you financially against certain covered bodily injury or property damage claims for which you are legally responsible.
Additional Living Expenses
If a covered loss makes the home temporarily uninhabitable, coverage may help pay certain additional living expenses while repairs are being made.
Medical Payments
Some policies provide limited medical-payments coverage for certain injuries to guests, regardless of fault, subject to policy terms.
Other Structures
Depending on the policy, qualifying sheds, detached garages and other structures may be eligible for coverage.
Mobile Home vs. Manufactured Home
The terms are frequently used interchangeably in everyday conversation, but there is a technical distinction.
Mobile Home
HUD uses the term mobile home for qualifying factory-built homes constructed before the federal Manufactured Home Construction and Safety Standards took effect on June 15, 1976.
Older homes can be more challenging to insure because carrier eligibility requirements vary.
Manufactured Home
Manufactured homes are factory-built homes constructed to the federal HUD Code and transported to the property in one or more sections on a permanent chassis.
A HUD certification label is placed on qualifying manufactured-home sections when they are produced.
Coverage Deserves a Closer Look in Texas
When comparing manufactured home insurance, don’t look only at the premium. Review what the policy covers, how losses are valued and which deductibles apply.
Wind & Hail
Wind and hail coverage, exclusions and deductibles can vary by carrier and location. Review these provisions before a storm occurs.
Flood
Flood coverage is generally separate from a standard home insurance policy. Properties with flood exposure should consider whether separate flood insurance is appropriate.
Home Condition
Age, roof condition, electrical systems, plumbing, heating and other property characteristics may affect carrier eligibility.
Deductibles
Review the deductibles that apply to covered losses, including any separate wind or hail deductibles included in the policy.
Replacement Cost vs. Actual Cash Value
Texas Department of Insurance recommends asking how your home and personal property will be valued before choosing a policy.
Replacement Cost
Replacement-cost coverage generally bases covered losses on the cost to repair or replace covered property with similar property, subject to policy terms and limits.
The exact settlement method can vary, so review the policy carefully.
Actual Cash Value
Actual-cash-value coverage generally considers depreciation when determining the value of covered damaged property.
That can result in a lower claim payment than replacement-cost coverage for some losses.
Learn more from the Texas Department of Insurance.
What Can Affect Your Mobile Home Insurance Options?
Insurance companies have different underwriting guidelines. These are some of the factors that may influence eligibility, coverage and price.
Year Built
Older manufactured and mobile homes may have different carrier eligibility requirements.
Home Condition
Roof, plumbing, electrical systems and overall property condition can affect underwriting.
Location
Weather exposure, protection class and other geographic factors can influence available options.
Occupancy
Owner-occupied, seasonal, rental and vacant homes can have different insurance requirements.
Additions
Decks, porches, rooms and other attached improvements should be disclosed when requesting coverage.
Claims History
Prior property losses may affect carrier eligibility and premium.
Owned Land vs. a Leased Mobile Home Lot
You can potentially insure a manufactured home whether you own the land beneath it or lease a site in a manufactured-home community.
Home on Land You Own
Tell us about the residence, acreage or lot, detached structures, fencing and other property features that may need to be considered.
Home on a Leased Lot
If your home is located in a manufactured-home community or on rented land, the home can still potentially be insured even though you don’t own the underlying land.
Community rules or lease requirements should also be reviewed when selecting coverage.
Coverage That May Require Special Attention
A home policy does not automatically cover every possible cause of loss or every property exposure.
Flood Insurance
Standard home insurance generally does not cover flood damage. Separate flood insurance may be available.
Wind & Hail
Availability, deductibles and exclusions can vary, particularly in areas with significant wind or storm exposure.
Earth Movement
Earthquake and certain earth-movement losses are commonly excluded unless coverage is specifically provided.
Home-Based Business
Business property and business liability may not be adequately protected by a standard personal policy.
Vehicles & Recreational Equipment
Autos, motorcycles, boats, ATVs and RVs typically require their own insurance coverage.
Valuable Property
Jewelry, collectibles, firearms and other valuable property can be subject to special limits or requirements.
Can an Older Mobile Home Still Be Insured?
Possibly. Insurance-company guidelines can vary considerably for older mobile and manufactured homes. The home’s age, condition, roof, electrical system, plumbing, location and other characteristics may affect available options.
If another company has told you that your home is too old to insure, it may still be worth allowing an independent agency to review the property and available markets.
An Independent Agency Can Compare Options
Manufactured-home underwriting can vary from one insurance company to another.
Multiple Carriers
We can review available options from multiple participating insurance companies rather than limiting you to one carrier.
Help Understanding Coverage
We can help you compare deductibles, limits, settlement options and important policy differences.
Texas-Based Service
Lavon Insurance is a local independent agency serving manufactured-home owners in North Texas and throughout the state.
Three Steps to Compare Mobile Home Insurance
Tell Us About the Home
Provide information about the home’s age, size, location, condition, ownership and current coverage.
We Review Available Markets
We compare available options from participating carriers whose underwriting guidelines fit the property.
Review Your Options
Compare coverage, deductibles and premiums and choose the option that fits your insurance needs.
Build Your Personal Insurance Plan
Home Insurance
Learn more about coverage for traditional site-built homes in Texas.
Explore Home Insurance →Personal Lines Insurance
Explore auto, recreational vehicle, property and other personal insurance options.
Explore Personal Insurance →Umbrella Insurance
Review additional personal liability protection above qualifying underlying policies.
Explore Umbrella Insurance →Mobile Home Insurance in North Texas
Lavon Insurance serves manufactured and mobile home owners in Lavon, Wylie, Princeton, Farmersville, Josephine, Nevada, Royse City, Rockwall, Greenville, Melissa and communities throughout Texas.
Whether your home sits on property you own or on a leased lot in a manufactured-home community, we can help review available insurance options.
Texas Mobile Home Insurance FAQs
What does mobile home insurance cover?
Depending on the policy, mobile or manufactured home insurance may provide coverage for the home, personal belongings, personal liability, additional living expenses and certain other structures.
What is the difference between a mobile home and a manufactured home?
Under HUD terminology, factory-built homes constructed before June 15, 1976 are generally referred to as mobile homes. Homes built after that date to the federal Manufactured Home Construction and Safety Standards are manufactured homes.
Can I insure an older mobile home?
Possibly. Insurance eligibility varies by carrier and may depend on the home’s age, condition, roof, electrical system, plumbing, location and other underwriting factors.
Can I insure a manufactured home if I don’t own the land?
Yes, coverage may be available when you own the manufactured home but lease the lot or land beneath it. Community or lease requirements may also affect the coverage you need.
Does mobile home insurance cover flood damage?
Standard home insurance generally does not cover flood damage. Separate flood insurance may be available depending on the property and location.
Does mobile home insurance cover wind and hail?
Wind and hail coverage can vary by insurance company, location and policy. Review exclusions, deductibles and coverage limits carefully before selecting a policy.
What is the difference between replacement cost and actual cash value?
Replacement-cost coverage generally does not deduct depreciation when determining the cost of repairing or replacing covered property, while actual cash value generally considers depreciation. The exact method depends on the policy.
Are my belongings covered inside a manufactured home?
Personal-property coverage may help protect qualifying furniture, clothing, electronics and other belongings against covered losses, subject to policy limits and exclusions.
Are decks, porches and sheds covered?
Coverage depends on how the structure is built, whether it is attached to the home and the specific insurance policy. Tell your agent about decks, porches, sheds, garages and additions so they can be properly considered.
How much mobile home insurance do I need?
The appropriate amount depends on the value of the home, how covered losses are valued, the amount of personal property you own, liability needs and other property characteristics.
Can Lavon Insurance compare manufactured home insurance companies?
Yes. Lavon Insurance is an independent insurance agency and can compare available manufactured and mobile home insurance options from multiple participating carriers.
Compare Mobile Home Insurance in Texas
Tell us about your mobile or manufactured home and Lavon Insurance can help you compare available coverage from multiple insurance carriers.
Insurance coverage, eligibility, limits, deductibles, exclusions and availability vary by insurance company and policy. This page provides general information and does not change or replace the terms of an insurance policy. Contact Lavon Insurance for coverage information specific to your home.