Equipment Breakdown Insurance in Texas
Your business depends on equipment that works. When a critical machine, electrical system, HVAC unit or refrigeration system suddenly stops, equipment breakdown insurance can help with certain covered losses.
- ✓ Independent agency
- ✓ Multiple commercial carriers
- ✓ Serving businesses across Texas
When Your Equipment Stops, Your Business Doesn’t Always Get to Stop
Modern businesses rely on equipment every day. HVAC systems keep customers and employees comfortable. Refrigeration keeps inventory at the right temperature. Electrical systems keep the lights, computers and machinery running.
A sudden equipment failure can create more than a repair bill. Depending on the policy, a breakdown may also lead to damaged property, spoiled inventory, extra expenses or an interruption to normal business operations. Equipment breakdown coverage is designed to address certain covered losses resulting from these unexpected failures.
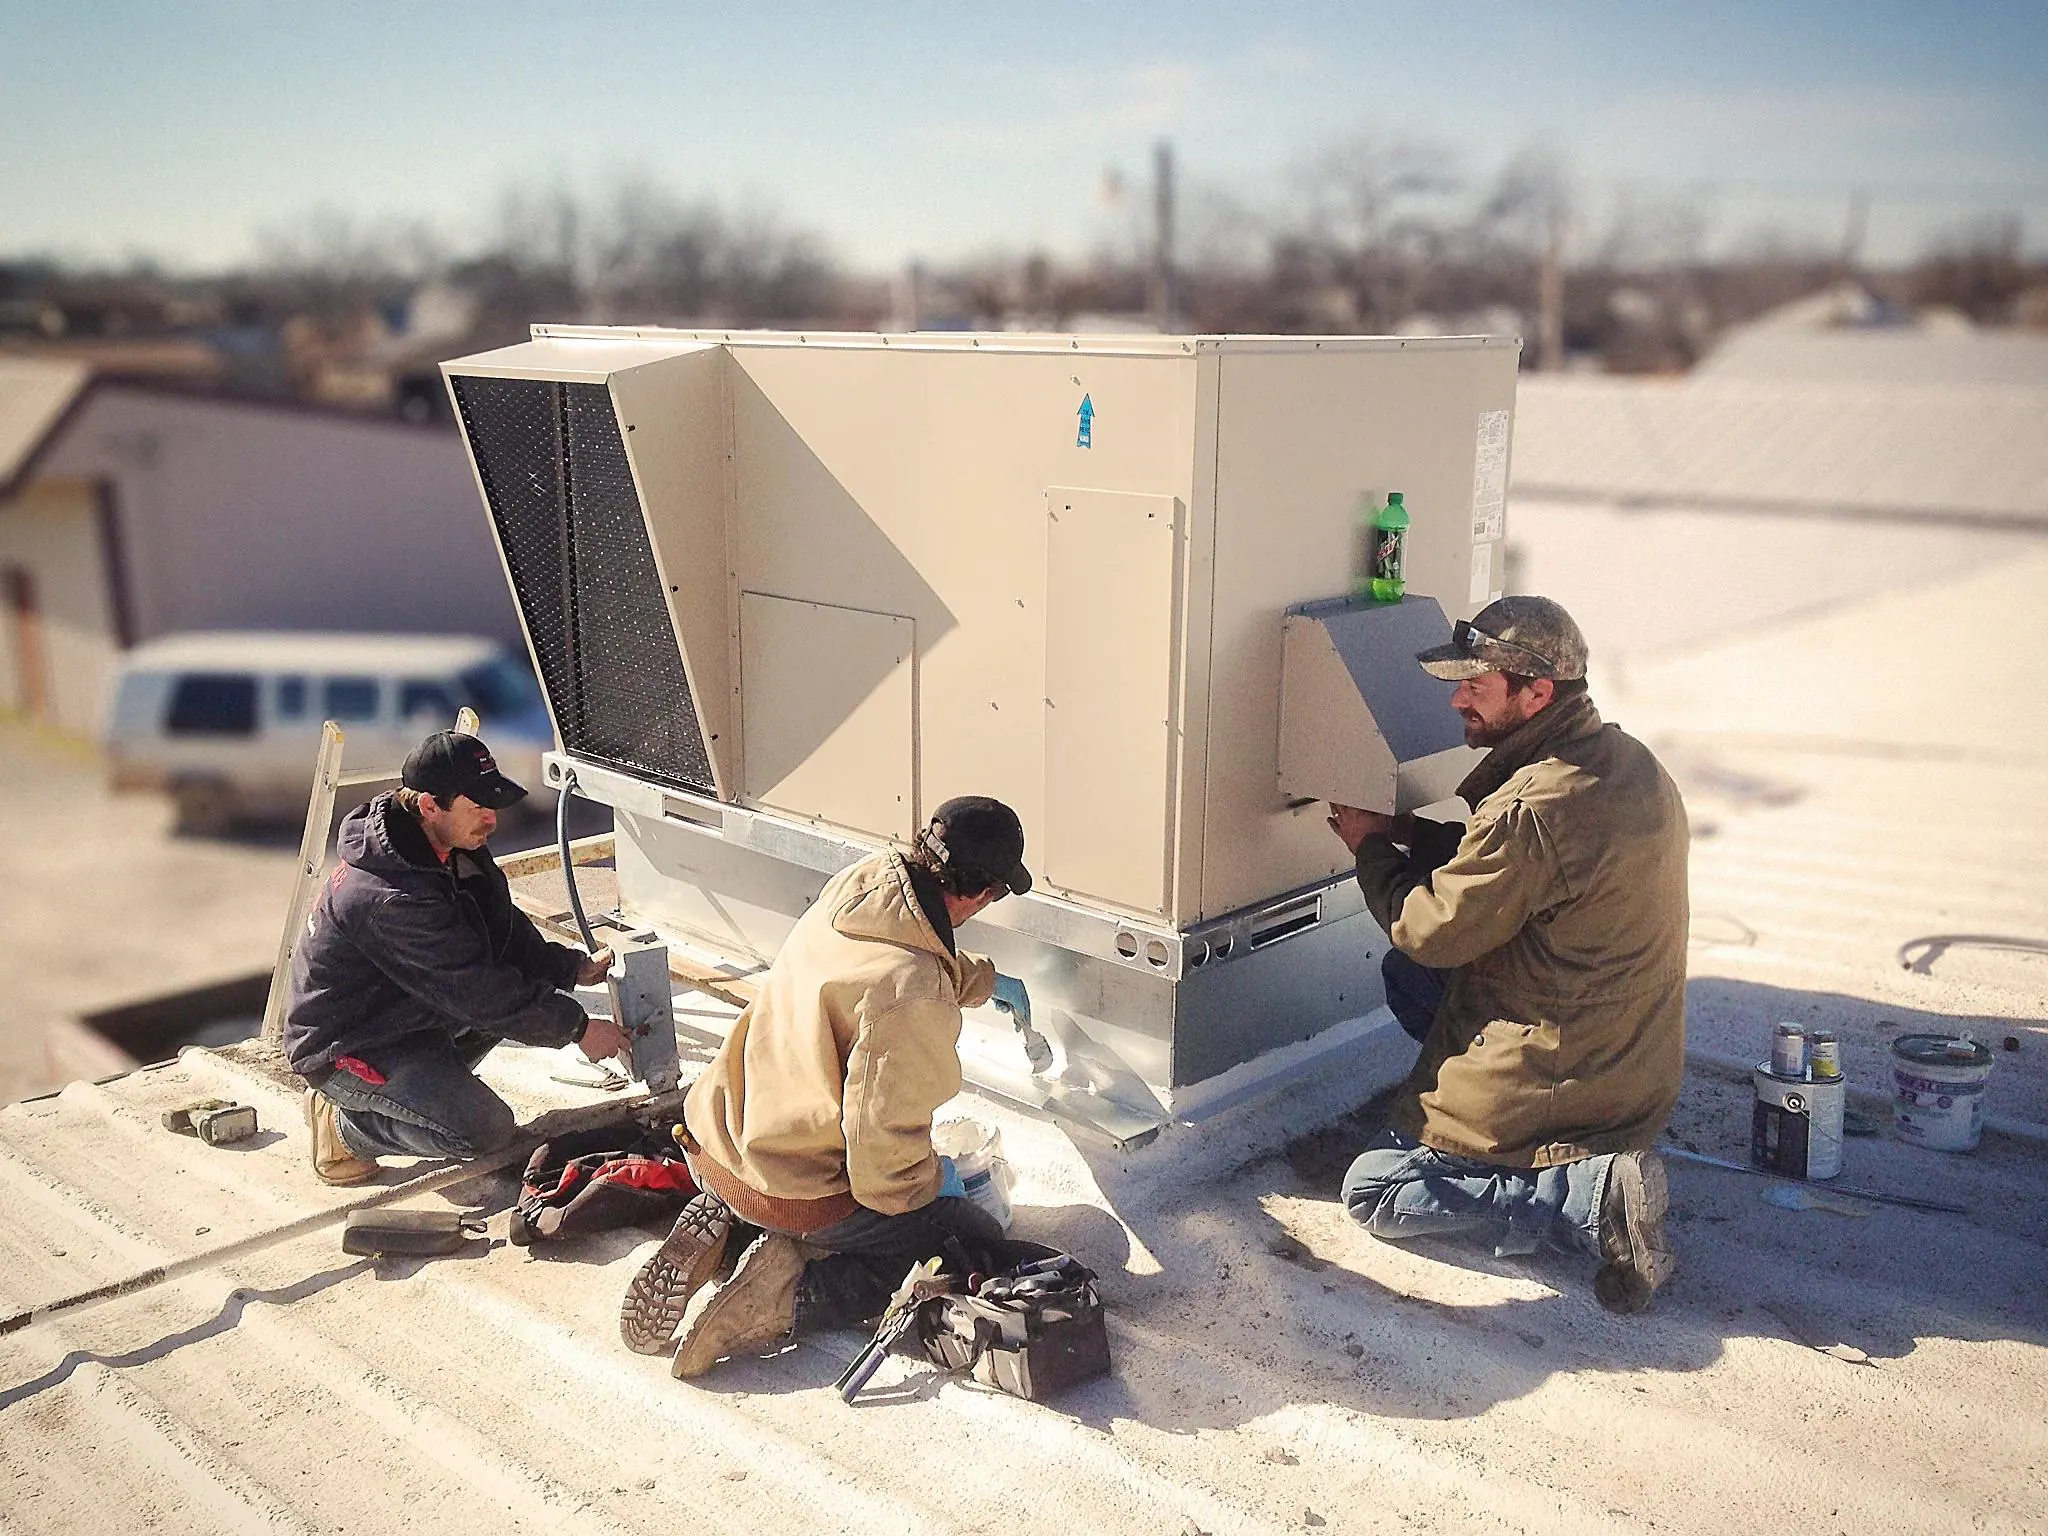
Equipment breakdown coverage, historically called boiler and machinery coverage, can apply to equipment such as boilers, air-conditioning units, compressors, commercial cooking equipment and water heaters. Coverage varies by policy and insurer.
What Equipment Breakdown Insurance May Help Cover
Policies can be built around the equipment and systems your operation depends on.
Mechanical Equipment
Certain covered mechanical equipment can include machinery, compressors, pumps and other essential systems used in business operations.
Electrical Systems
Depending on the policy, covered electrical equipment and systems may be protected against certain sudden and accidental breakdowns, including some power surge losses.
HVAC & Refrigeration
Heating, ventilation, air-conditioning and refrigeration equipment can be especially important to restaurants, retailers, warehouses and other businesses.
Computers & Electronics
Some equipment breakdown policies can address certain covered damage involving computer, communication and other electronic equipment.
Spoilage
Businesses that depend on refrigeration may have additional exposure when equipment failure affects perishable inventory. Coverage is subject to the policy.
Business Interruption
Some equipment breakdown coverage can include certain business income, extra expense or expediting costs resulting from a covered breakdown.
Equipment Breakdown vs. Commercial Property Insurance
Commercial property insurance and equipment breakdown coverage address different types of risks.
| Coverage | Generally Designed to Address |
|---|---|
| Commercial Property | Covered damage to buildings, contents and other business property from perils such as fire, wind and theft. |
| Equipment Breakdown | Certain sudden and accidental mechanical or electrical breakdown losses, which many property policies exclude. |
| Business Income | Certain income losses and continuing expenses following an eligible covered loss, subject to the policy. |
Businesses That May Depend on Equipment Breakdown Coverage
If a single equipment failure could shut your doors for a day, it’s worth a closer look.
Restaurants
Commercial ovens, refrigeration, HVAC and other equipment can be essential to daily operations.
Retail Businesses
Electrical systems, refrigeration, security systems and other equipment may be critical to keeping a store operating.
Manufacturing
Production machinery and electrical systems can play a central role in keeping operations moving.
Property Owners
HVAC, electrical and other building systems can be important for commercial properties and tenants.
Warehouses
Refrigeration, electrical equipment and material-handling systems may be essential to warehouse operations.
Professional Offices
Computers, communication systems, HVAC and other electronic equipment can be critical to keeping an office productive.
What Happens When Critical Equipment Fails?
Imagine your commercial refrigeration system fails on a Friday afternoon. The repair technician is on the way, but your business still has a problem: the equipment isn’t running, customers are waiting and inventory could be at risk.
Depending on the cause of the breakdown and the coverage purchased, equipment breakdown insurance may help with eligible repair or replacement costs and certain related losses. Some policies may also provide coverage for spoilage, expediting expenses or business interruption.
That’s why equipment breakdown insurance isn’t simply about the machine. It’s about the potential financial impact when an important part of your business suddenly stops working.
Equipment breakdown coverage is generally meant for sudden and accidental failures, not wear and tear. Good maintenance protects both your equipment and your claim. Many businesses consider:
- Following manufacturer maintenance schedules and keeping service records
- Having HVAC and refrigeration serviced before Texas summer heat peaks
- Installing surge protection on electrical panels and sensitive electronics
- Using temperature alarms on coolers and freezers
- Keeping a list of repair vendors and lead times for critical parts
- Replacing equipment nearing the end of its useful life
Some carriers offer inspection or loss-prevention services with equipment breakdown policies.
Equipment Breakdown Insurance FAQs
What is equipment breakdown insurance?
Equipment breakdown insurance is commercial coverage designed to address certain losses resulting from covered mechanical, electrical or other equipment breakdowns. Depending on the policy, it may address repair or replacement costs and certain related losses.
Is equipment breakdown covered by commercial property insurance?
Not necessarily. Commercial property policies vary, and certain mechanical or electrical breakdown losses may require separate equipment breakdown coverage or an endorsement. Your agent can review your policy to identify potential gaps.
Does equipment breakdown insurance cover HVAC equipment?
HVAC equipment, including air-conditioning units, can be eligible under equipment breakdown coverage, depending on the policy and cause of loss.
Can equipment breakdown insurance cover lost business income?
Some equipment breakdown policies can provide coverage for certain business interruption or income losses resulting from a covered breakdown. The amount and circumstances of coverage depend on the policy. Learn more about business income insurance.
Does equipment breakdown insurance cover normal wear and tear?
Equipment breakdown coverage is generally intended for covered sudden and accidental breakdowns rather than ordinary wear and tear or maintenance issues. Specific exclusions vary by policy.
Can equipment breakdown coverage be added to a BOP?
Some insurance companies offer equipment breakdown coverage as an option or endorsement on a business owner’s policy. Your available options depend on the insurance carrier and policy.
Build a Business Insurance Plan Around How Your Business Works
Equipment doesn’t operate in a vacuum. Your business may also need other property, income and liability coverage.
Commercial Property
Coverage for eligible commercial buildings and property.
Learn more →Business Personal Property
Help protect eligible equipment, inventory, furniture and other business contents.
Learn more →Business Income
Coverage that may help address certain income losses following an eligible covered loss.
Learn more →Inland Marine
Coverage options for tools and equipment that move between job sites.
Learn more →Business Owner’s Policy
Combine important business coverages in one commercial insurance package.
Learn more →Cyber Insurance
Learn about insurance options for certain cyber-related risks to your systems and data.
Learn more →Let’s Make Sure Your Equipment Has a Backup Plan
Your business has enough surprises already. Let’s look at the equipment and systems you depend on and discuss insurance options that may fit your business.
Insurance coverage is subject to policy terms, conditions, limits, exclusions and endorsements. Equipment breakdown coverage varies by insurance carrier and policy. This page is for general informational purposes and is not a contract or guarantee of coverage. Please review your policy and speak with your insurance agent about your specific business and coverage needs.