Motor Truck Cargo Insurance in Texas
Protect the freight your trucking business is responsible for while it is on your truck. Lavon Insurance helps Texas owner-operators, motor carriers and fleets compare cargo insurance based on what you haul, how much it is worth and what your brokers and shippers require.
- Covers qualifying freight in your care, custody or control
- Theft, collision, fire and other covered causes of loss
- Limits set to your highest-value load and contracts
- Reefer breakdown available by endorsement
- For owner-operators, motor carriers and small fleets
Protect the Freight You Haul
Motor truck cargo insurance covers loss of or damage to qualifying freight while it is in your care, custody or control, subject to the policy’s terms, limits, exclusions and endorsements. A single damaged or stolen load can be worth more than the truck that was hauling it.
Cargo coverage is separate from commercial truck liability, which covers injury and damage you cause to others, and truck physical damage, which covers your own equipment.
What Motor Truck Cargo Insurance Can Cover
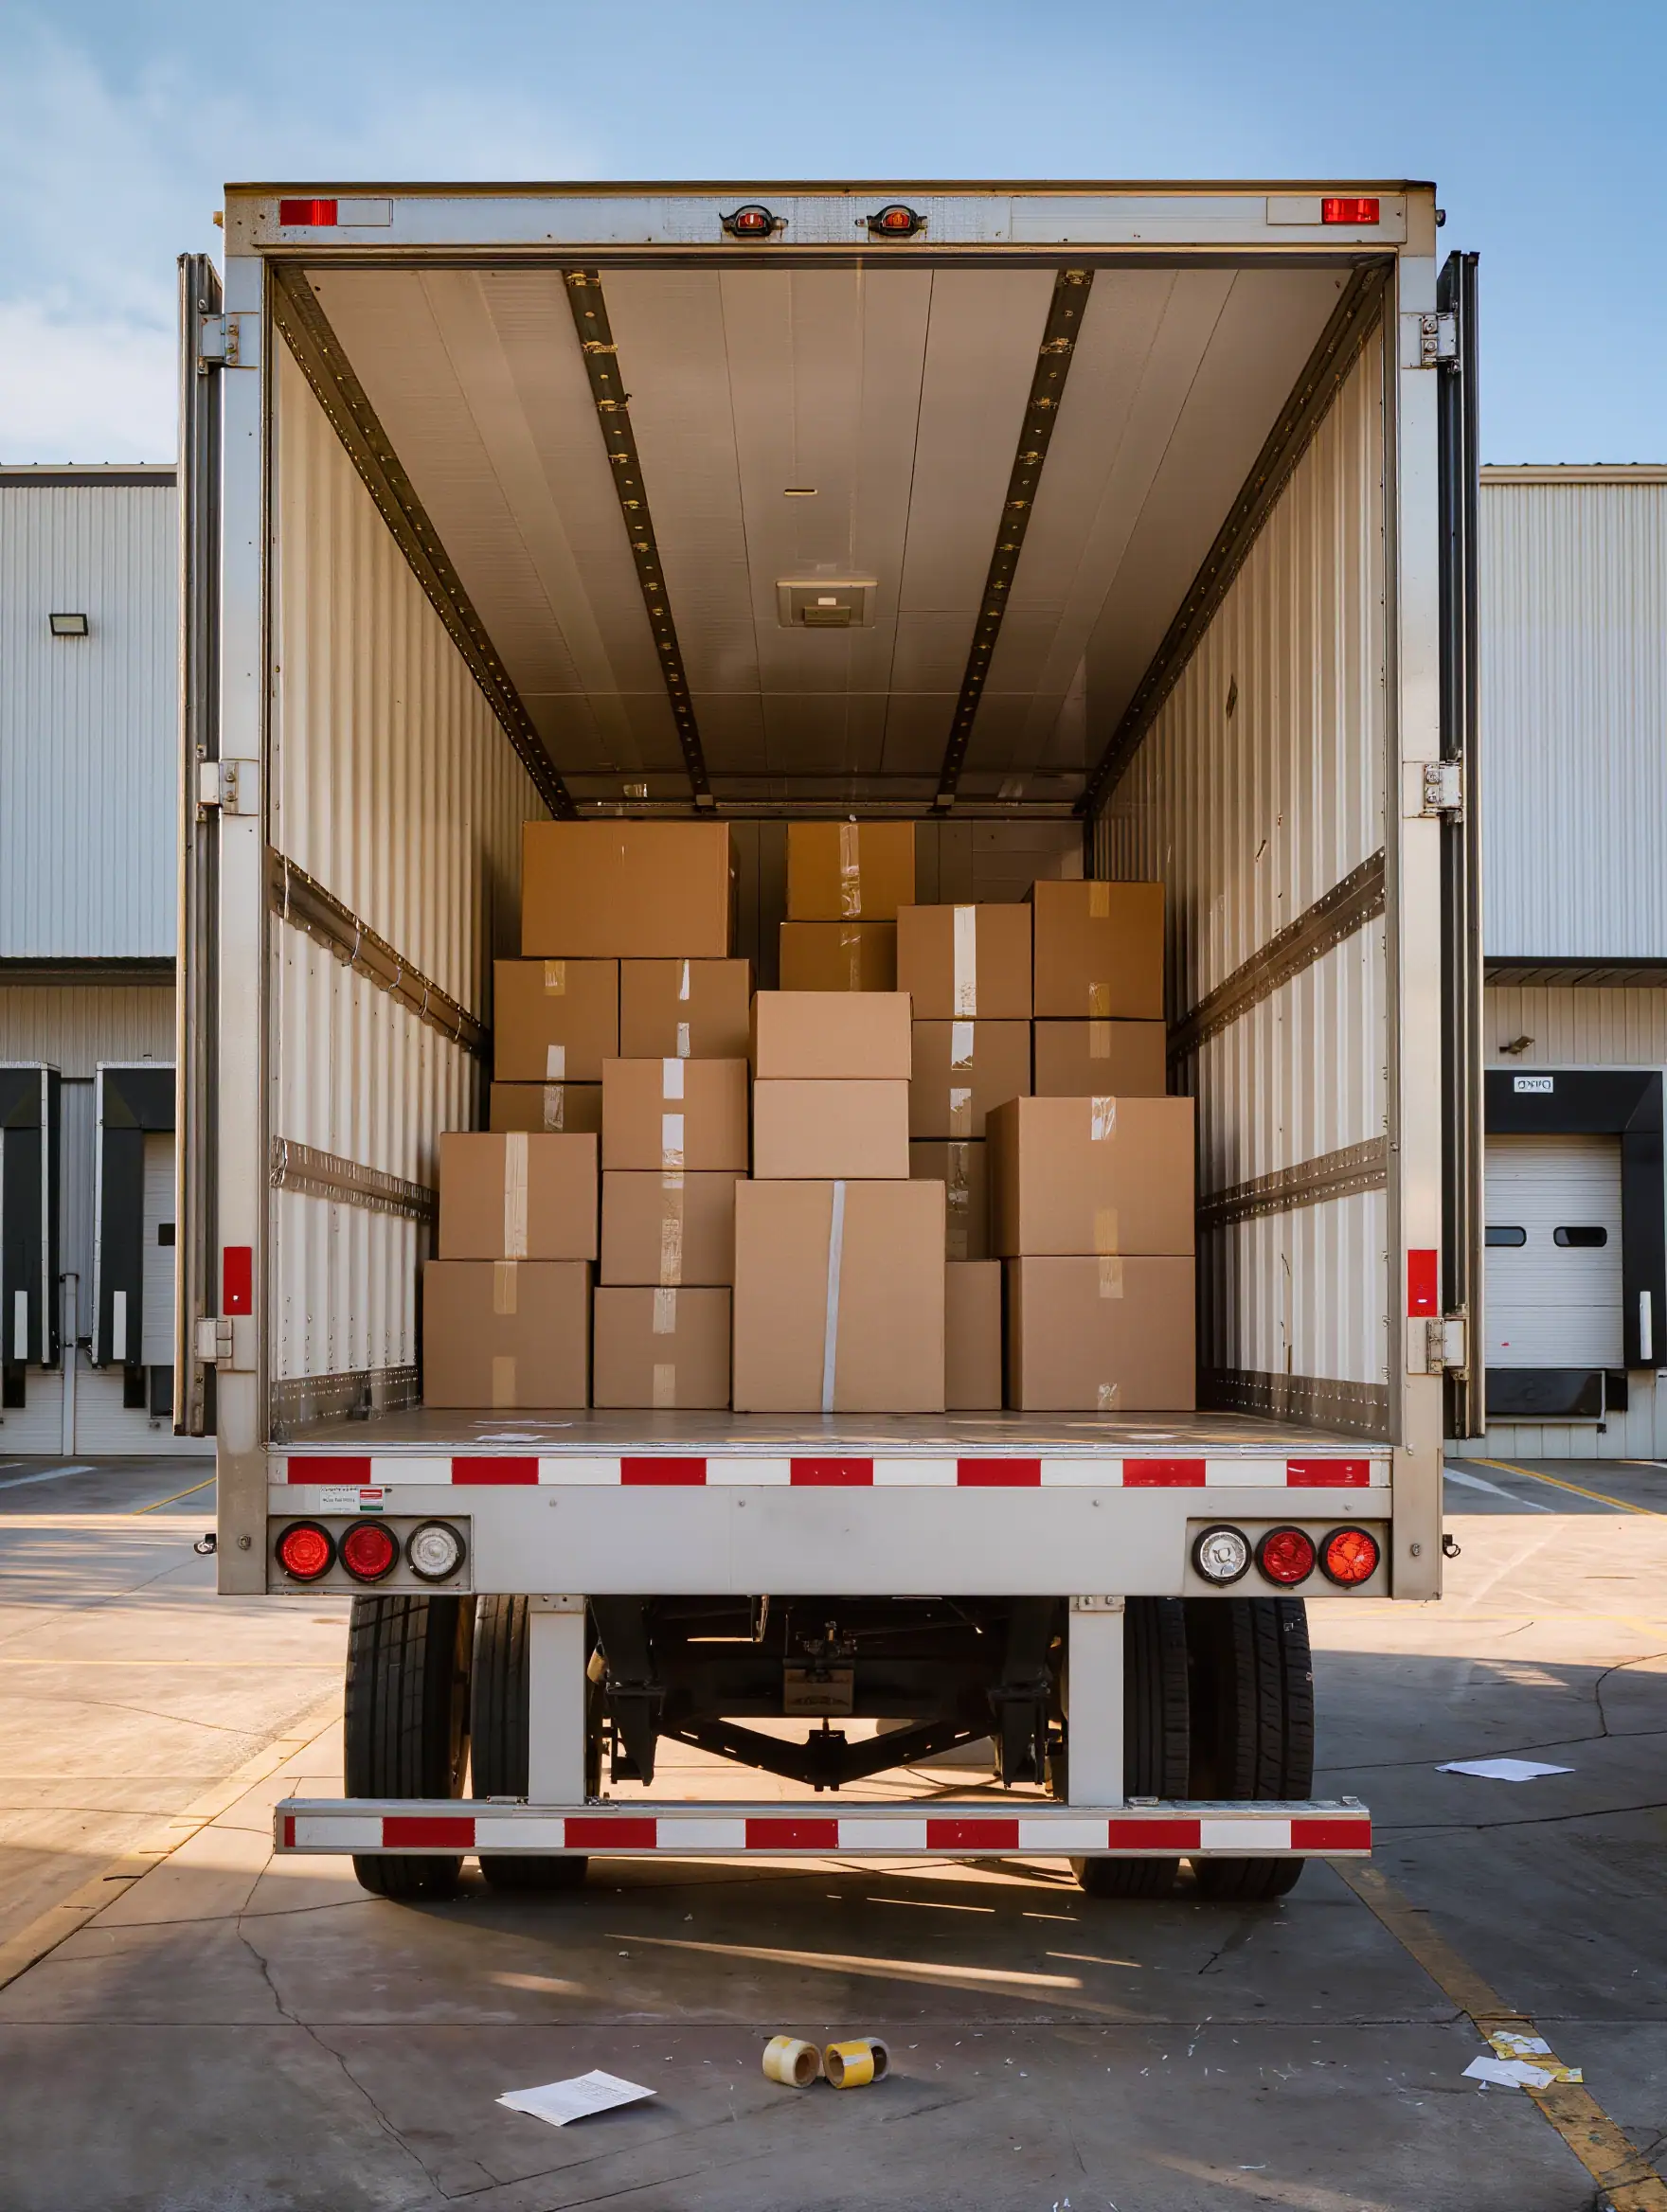
Coverage depends on the insurance company, policy form, commodity, endorsements and the circumstances of the loss. Common covered exposures can include:
- Collision and overturn: freight damaged when the truck is in an accident
- Cargo theft: stolen loads, subject to the policy’s security conditions
- Fire and explosion: freight destroyed or damaged by fire on the road
- Weather: covered damage from wind, hail and other named causes
- Loading and unloading: damage during handling, depending on policy wording
- Refrigerated loads: spoilage from reefer unit breakdown, when endorsed
- Debris removal: cleanup of damaged freight after a covered loss, on many policies
Cargo Policy Exclusions and Conditions to Review
Cargo policies vary more than almost any other trucking coverage. These are the provisions that most often decide whether a claim is paid.
Commodity Exclusions
Many policies exclude or limit certain freight, such as alcohol, tobacco, electronics or livestock. Confirm every commodity you haul is accepted.
Unattended Vehicle
Theft coverage may be restricted when a loaded truck or trailer is left unattended, depending on where and how it is parked.
Security Requirements
Some policies require locks, alarms, kingpin locks or secured lots for theft coverage to apply.
Reefer Breakdown
Spoilage from refrigeration unit failure is often excluded unless a reefer breakdown endorsement is added.
Sublimits
A policy may pay less than the full limit for certain losses, such as theft or specific commodities.
Delay and Loss of Market
Losses caused only by late delivery or a drop in market value are commonly excluded.
How Much Motor Truck Cargo Insurance Do You Need?
There is no single right limit. Brokers and shippers commonly ask for $100,000 in cargo coverage, and some require $150,000, $250,000 or more for higher-value freight.
| What to Check | Why It Matters |
|---|---|
| Your highest-value load | If a load is worth more than your cargo limit, you could pay the difference after a total loss. |
| Broker and shipper contracts | Many contracts set a minimum cargo limit and may require reefer breakdown or other endorsements before you can haul. |
| Per-vehicle vs. per-occurrence limits | Some policies cap what they pay per truck and separately per loss event or location. |
| Deductible | A higher deductible lowers premium but raises what you pay on every cargo claim. |
| Sublimits | Theft or specific commodities may have a lower limit than the policy’s main cargo limit. |
| Terminal or storage coverage | Freight sitting at your yard or terminal may need coverage beyond what applies in transit. |
Compare the value of your most expensive regular load with your cargo limit. If the load is worth more, talk with us about a higher limit or a per-load increase before you haul it.
Is Motor Truck Cargo Insurance Required in Texas?
What the Law Requires
For most general freight carriers, cargo insurance is not required by federal or Texas law. The main exception is household goods movers: the FMCSA requires interstate household goods carriers to file cargo coverage, and Texas requires intrastate household goods carriers to carry $5,000 per vehicle and $10,000 aggregate cargo coverage.
Sources: FMCSA Insurance Filing Requirements and Texas Department of Motor Vehicles
Even when the law does not require it, most brokers and shippers will not load you without proof of cargo coverage. They usually set the minimum limit in their carrier agreement and verify it through your certificate of insurance.
Motor carriers that lease on owner-operators may also require the owner-operator to carry cargo coverage or reimburse cargo claims under the lease.
Reefer Cargo Insurance in Texas
Refrigerated loads depend on holding a set temperature for the whole trip. A refrigeration unit failure, fuel outage or temperature change can lead to spoiled or rejected freight.
Standard cargo policies often exclude spoilage from mechanical breakdown, so reefer carriers typically need a reefer breakdown endorsement. If you haul food, produce, pharmaceuticals or other temperature-sensitive freight, tell us when you request a quote.
What Reefer Underwriters Ask About
- Commodities you haul and typical load values
- Age and maintenance records of your reefer units
- Temperature recorders or monitoring you use
- Pre-cooling and load inspection procedures
- Customer requirements for reefer coverage
- Prior spoilage or rejected-load claims
Motor Truck Cargo vs. Other Trucking Insurance
A trucking program contains several coverages. Each one addresses a different exposure.
| Coverage | What It Covers |
|---|---|
| Motor truck cargo | Covered loss of or damage to qualifying freight you are hauling |
| Commercial truck liability | Covered bodily injury and property damage you cause to others |
| Truck physical damage | Covered damage to your own insured truck and equipment |
| Trailer interchange | Covered damage to non-owned trailers under an interchange agreement |
| Trucking general liability | Certain non-auto liability claims tied to your business |
See how these fit together in our guide to trucking insurance policies, or start with our overview of trucking insurance in Texas.
Cargo Insurance for Texas Trucking Businesses
Owner-Operators
Independent drivers hauling under their own authority, or leased on where the lease requires cargo coverage.
Motor Carriers
Companies responsible for customer freight under their own authority and broker agreements.
Small Fleets
Growing fleets that need limits to keep pace with more trucks, customers and higher-value loads.
General Freight Haulers
Dry van and flatbed carriers moving common freight across Texas and beyond.
Refrigerated Carriers
Reefer operations that need spoilage and reefer breakdown coverage.
Specialized Haulers
Carriers moving equipment, building materials or high-value freight that need higher limits.
Getting a Motor Truck Cargo Insurance Quote
Lavon Insurance is an independent agency. We compare cargo coverage from multiple insurers that work with Texas trucking businesses.
Tell Us What You Haul
Your commodities, typical and maximum load values, operating radius and any reefer or specialized freight.
We Compare Options
We match your freight and contract requirements to cargo policies, limits and endorsements that fit.
You Choose Your Coverage
Pick your limit and deductible, and we provide the certificates your brokers and shippers need.
Frequently Asked Questions About Motor Truck Cargo Insurance
What is motor truck cargo insurance?
Motor truck cargo insurance covers loss of or damage to qualifying freight while it is in a trucking company’s care, custody or control, subject to the policy’s terms, limits and exclusions.
Is motor truck cargo insurance required in Texas?
For most general freight carriers, cargo insurance is not required by federal or Texas law. Household goods movers are the main exception. However, most brokers and shippers require proof of cargo coverage before they will load you.
How much cargo insurance does a trucking company need?
Brokers and shippers commonly require $100,000 in cargo coverage, and some require $150,000 to $250,000 or more. Your limit should also be at least the value of your most expensive regular load.
Does cargo insurance cover theft?
Many cargo policies cover theft, but coverage often depends on conditions such as security requirements and unattended vehicle rules, and theft may carry a sublimit.
Does cargo insurance cover refrigerated freight?
Cargo policies can cover refrigerated freight, but spoilage caused by a refrigeration unit breakdown usually requires a reefer breakdown endorsement.
Does motor truck cargo insurance cover my truck?
No. Cargo insurance covers the freight you haul. Damage to your own truck is covered by truck physical damage insurance.
What is the difference between cargo and liability insurance?
Cargo insurance covers the freight you are hauling. Commercial truck liability covers bodily injury and property damage you cause to others while operating your truck.
Can an owner-operator get motor truck cargo insurance?
Yes. Owner-operators can buy cargo coverage whether they run under their own authority or are leased to a motor carrier that requires it.
Does cargo insurance cover every type of freight?
No. Most policies exclude or restrict certain commodities and may set sublimits for high-value freight, so every commodity you haul should be confirmed with the insurer.
What do I need for a cargo insurance quote?
Plan to share your commodities, typical and maximum load values, operating radius, authority or lease details, any reefer equipment, the limits your contracts require and your cargo loss history.
Motor Truck Cargo Insurance in Lavon & Throughout Texas
Whether you run one truck or a growing fleet, we help trucking businesses across Texas, including these North Texas communities:
Let’s Talk About Your Cargo Insurance
Your truck isn’t the only valuable thing on the road. Tell us what you haul, and we’ll compare cargo insurance options that fit your loads and contracts.
Insurance coverage, eligibility, limits, deductibles, exclusions, endorsements, pricing, filings and availability vary by insurance carrier, policy, commodity, business classification, operating authority and individual circumstances. This page is general information and is not a contract, legal advice, regulatory advice or a guarantee of coverage.